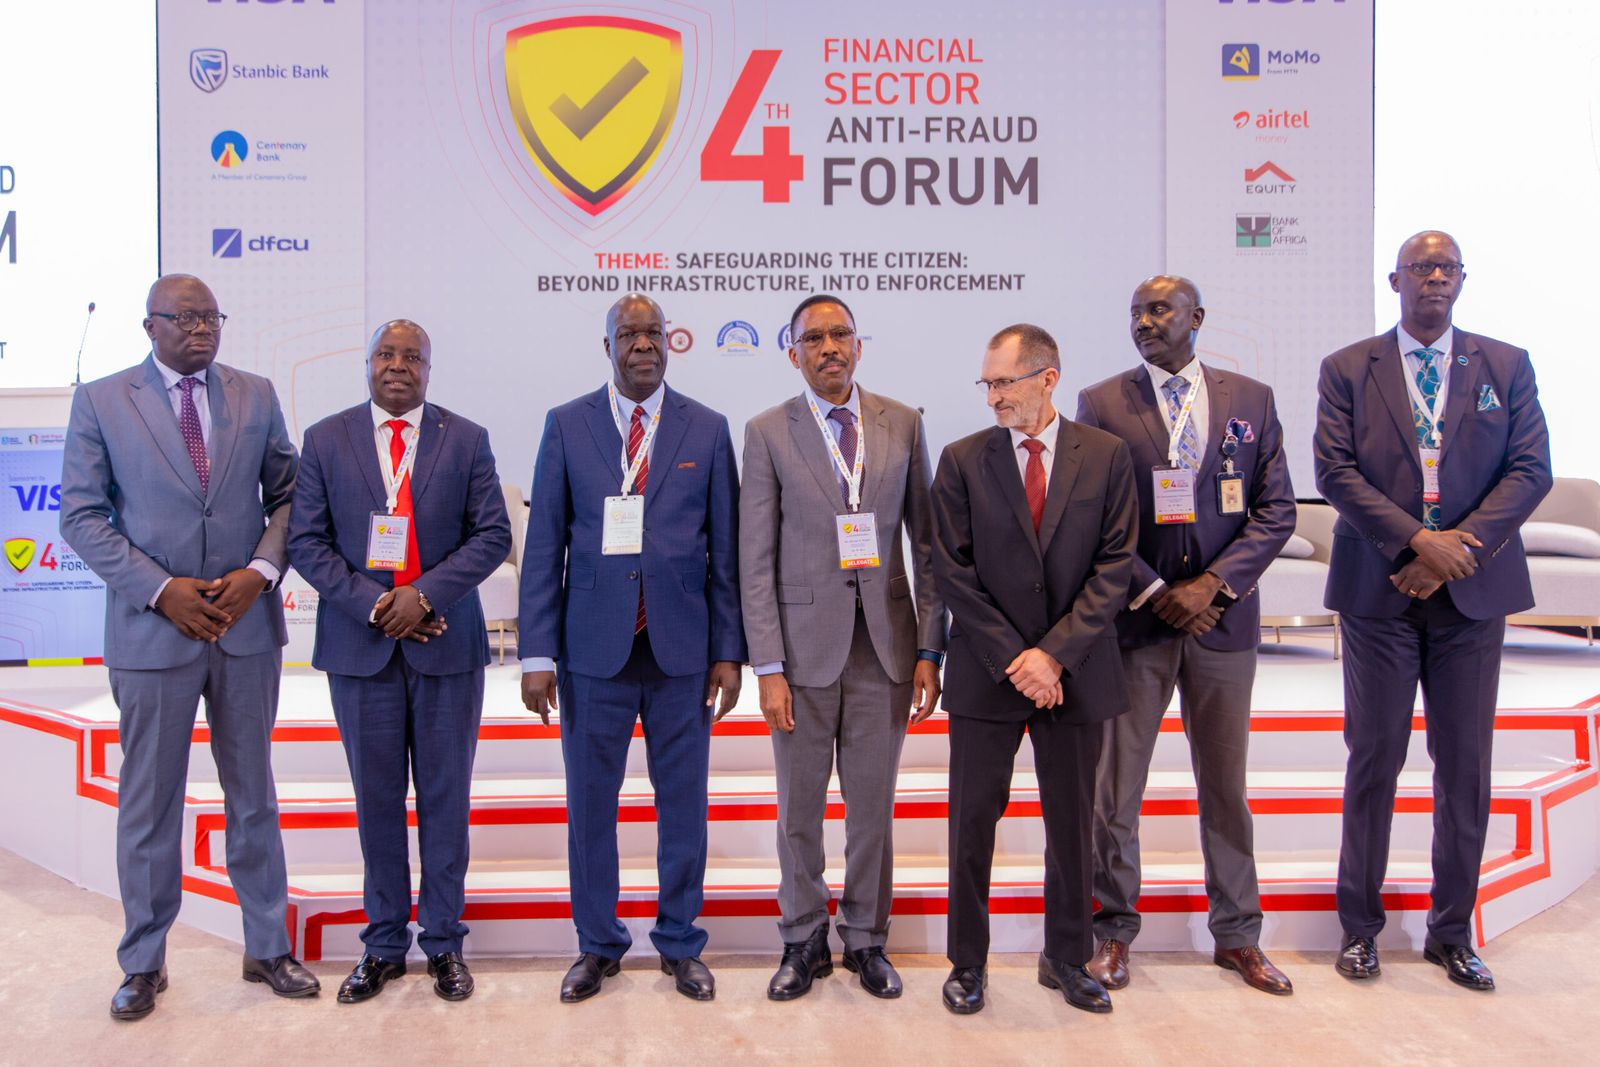


Uganda’s financial sector is turning its attention from simply building digital financial infrastructure to strengthening enforcement, consumer protection and institutional coordination as cyber and financial fraud becomes more sophisticated and costly.
That shift dominated the 4th Annual Financial Sector Anti-Fraud Forum 2026, held at the Kampala Marriott Hotel on September 23rd under the theme, “Safeguarding the Consumer: Beyond Infrastructure, Into Enforcement.”
The forum brought together banks, payment service providers, regulators, the Judiciary, law-enforcement agencies, telecommunications and technology players, development partners and other stakeholders to examine the vulnerabilities emerging alongside Uganda’s increasingly digital financial ecosystem.

The discussions came against a sobering backdrop. Between January and August 2026, Uganda’s financial sector recorded 6,533 reported cyber and fraud incidents, resulting in actual losses of UGX 24 billion, while the total suspected exposure at risk was estimated at UGX 68 billion, according to figures presented by Uganda Bankers’ Association Chairman Michael Mugabi.
The most persistent threats included peer-to-peer and wallet fraud, compromised digital channels, internal control and process abuse, fraudulent investment schemes and suspicious financial flows, alongside gaps in customer security awareness.
For Mugabi, those figures represent more than balance-sheet losses. Fraud, he argued, risks undermining public confidence at the same time that banks are seeking to bring millions more Ugandans and businesses into formal finance.
The banking industry aims to expand formal credit access from about 4.3 million individuals to more than 14.6 million Ugandans and increase the number of registered businesses accessing formal credit from about 70,000 to more than one million.
But such expansion ultimately depends on trust.
“Every fraud that goes unresolved, every scam that spreads unchecked, is a quiet tax on our ability to deliver that growth,” Mugabi said.
Banks have consequently been strengthening internal controls, staff vetting and fraud-risk systems, with some institutions elevating cyber and fraud governance to board level. UBA is also an anchor member of the Financial Sector Anti-Fraud Consortium, whose secretariat it hosts.
When fraud moves faster than justice
A major theme emerging from the forum was the widening speed gap between digital crime and the institutions responsible for investigating and prosecuting it.
Deputy Chief Justice Hon. Justice Moses Kazibwe Kawumi, representing the Chief Justice, said Uganda had invested considerably in mobile money, electronic banking, digital payments and telecommunications infrastructure. The next test, however, was how effectively institutions respond when those systems are abused.
“The transaction may occur in seconds; the investigation may take months; and the litigation may take years.”
Digital evidence can also be dispersed across platforms and altered or disappear quickly, making cooperation between banks, telecom operators, investigators, prosecutors and courts increasingly important.
The Judiciary is responding partly through digital transformation of its own. Its Electronic Court Case Management Information System is designed to automate and track cases from filing through disposition and appeal, while supporting electronic filing and payments.
The Judiciary is also strengthening data governance, cybersecurity and digital resilience and considering technology for court recording, transcription and online dispute resolution. Judicial officers are receiving training on digital evidence, cybercrime and emerging financial technologies.
Kawumi nevertheless stressed that courts cannot address digital financial crime alone. Banks and technology providers possess transaction logs and understand the technical architecture behind payment gateways, mobile-money platforms and digital wallets.
That makes stronger protocols for preserving digital evidence, authenticating electronic records, tracing transactions and responding to lawful information requests increasingly important.
A UGX 127 million lesson in digital trust
One of the forum’s most striking illustrations came through a fraud case clinic presented by the ISACA Kampala Chapter in partnership with ACFE.
The case examined a customer who disputed UGX127 million in 31 transactions during August 2026. Of the disputed amount, UGX83 million moved through 17 internet-banking transfers while UGX44 million went through 14 bank-to-wallet transactions. The customer did not dispute 11 ATM withdrawals worth UGX9 million.
The presentation used the case to illustrate how fraud can emerge not from one failed control, but from several weak points across an ecosystem.
Among the questions raised were whether customers fully understand digital services activated when opening accounts, why unused digital channels remain active, whether a new device should automatically trigger stronger authentication and how quickly banks and telecom operators should respond after a phone is reported stolen.
The clinic proposed a “trust by design” approach in which unused channels are disabled by default, new devices trigger additional verification and cooling-off periods, behavioural analytics flag unusual activity and banks and telecom companies share intelligence on suspicious wallets.
It also proposed a more integrated response in which a single fraud report could rapidly block access across a customer’s SIM, wallet and bank channels.
The underlying message was succinct: “Every fraud is a trust failure before it is a financial loss.”
From arrests to recovery
The forum also pushed the debate beyond detecting fraud toward what happens after money has disappeared.
Kawumi argued that the effectiveness of an anti-fraud system should not be measured solely by arrests and convictions. Institutions should also examine how much money victims recover, whether illicit proceeds are successfully traced and whether vulnerabilities that enabled fraud are subsequently closed.
UBA has similarly called for legal reforms, including stronger asset-tracing and recovery mechanisms, specialised capacity to investigate and prosecute complex financial and cybercrime, and ultimately a dedicated court equipped to handle such cases with greater speed and expertise.
The challenge is becoming particularly important as Uganda encourages consumers to adopt more digital financial services.
For the market vendor receiving digital payments, the boda rider using mobile money or the young professional opening a first bank account, the promise of digital finance depends not only on how quickly money can move, but also on what happens when something goes wrong.
That left the forum with a broader proposition for Uganda’s technology and financial sectors: building digital infrastructure was only the first stage.


